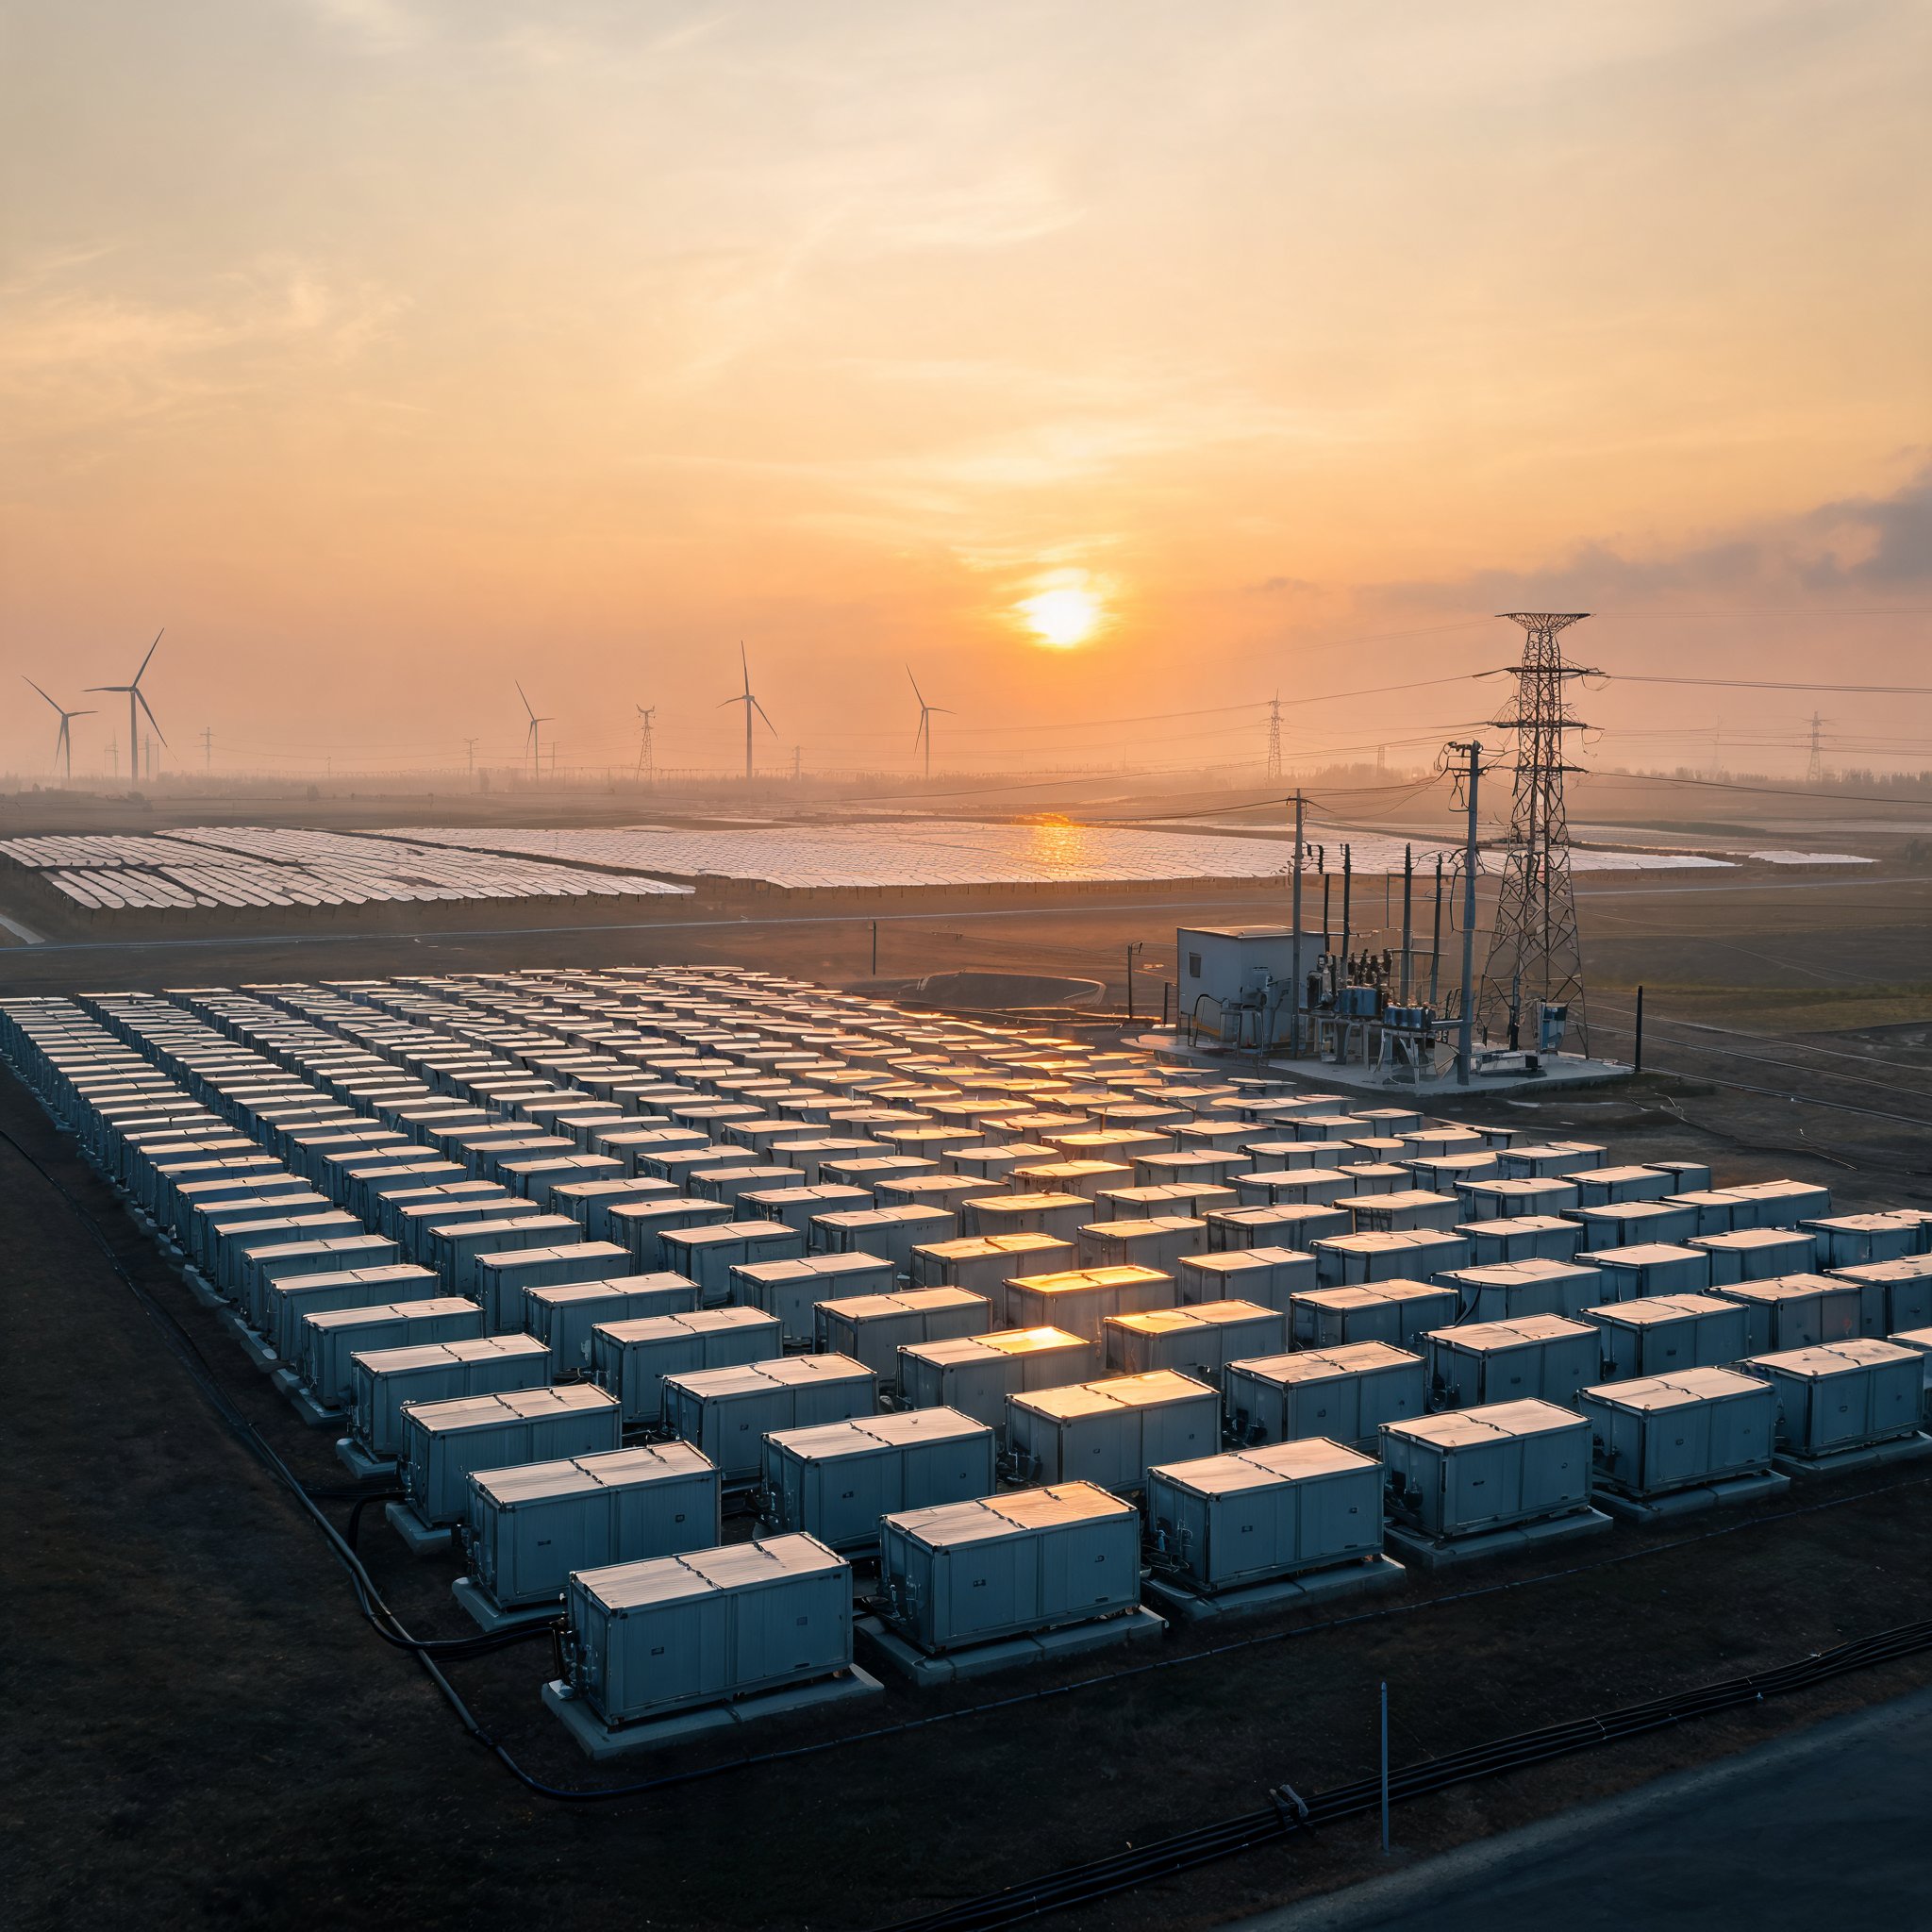
China's operational new-type energy storage capacity stood at 167 GW/435 GWh at the end of September 2026, 63% higher than a year earlier, according to figures the National Energy Administration (NEA) released on October 30.
The data were presented at the agency's quarterly press conference on national energy developments. China's new-type storage category covers electrochemical, compressed-air and other emerging storage systems, but excludes conventional pumped hydro.
Against 135.93 GW/351.12 GWh at the end of 2025, the latest figures point to a net addition of roughly 31 GW/84 GWh during the first nine months of 2026.
Duration and utilization both rise
Average storage duration increased to 2.61 hours, about 0.27 hours more than a year earlier. Equivalent utilization hours reached roughly 915 over the nine-month period, approximately 10 hours above the same stretch of 2025.
According to the NEA, the improvement indicates that the build-out is being accompanied by gradual changes in how storage systems are configured and operated, rather than growth in installed capacity alone. The agency attributed the rapid development of new-type storage to government policies, technological innovation, industrial supply chains and rising demand for flexibility in the power system.
Renewable growth underpins the need
China's combined wind and solar generating capacity exceeded 2.01 TW at the end of September, accounting for approximately 48.7% of total installed power capacity. As variable renewable generation expands, storage is increasingly called on to absorb surplus electricity, shift output to higher-demand periods and provide fast-response grid services.
A shifting market structure
Official figures for 2025 showed that independent energy storage facilities made up 51.2% of cumulative new-type storage installations. Projects rated at 100 MW or above represented 72% of installed capacity, while systems with durations of at least four hours accounted for 27.6%.
Lithium-ion batteries remained the dominant technology at approximately 96% of installed new-type storage capacity, although compressed-air, flow batteries and other technologies are gradually widening their presence.
Market reforms are expected to reinforce these trends. China has been developing arrangements that allow independent storage operators to earn revenue from electricity trading, ancillary services and capacity remuneration, gradually reducing reliance on mandatory storage requirements tied to renewable projects.
Under the country's 15th Five-Year Plan for power system development, new-type energy storage capacity is targeted at 300 GW by 2030, with greater emphasis on longer-duration systems, grid-forming capabilities and improved operational efficiency.
Storage's role in renewable-heavy grids
The contribution is already visible in regional grids with heavy renewable penetration. In western Inner Mongolia, the grid operator reported 20.23 GW/70.47 GWh of operational storage capacity in October. During emergency dispatch operations, storage supplied up to 12.25 GW, equivalent to 33% of the grid's electricity demand at the time.
Such cases illustrate how storage can deliver substantial short-term balancing capacity in systems with high shares of wind and solar. For other countries expanding renewable generation, China's deployment offers experience in large-scale storage manufacturing, grid integration and centralized dispatch.